The Big Story
Quick Take:
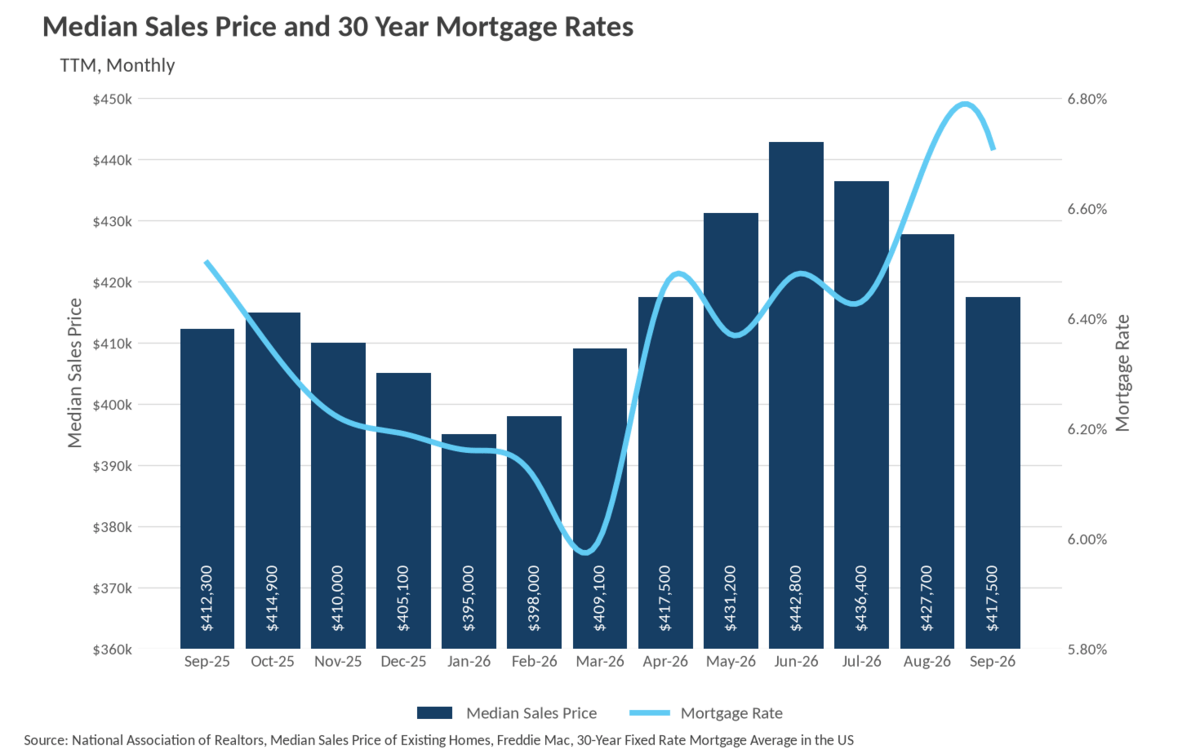
- Median home sale prices have declined for the third straight month, slipping to $417,500 in September, though they remain slightly above where they were a year ago.
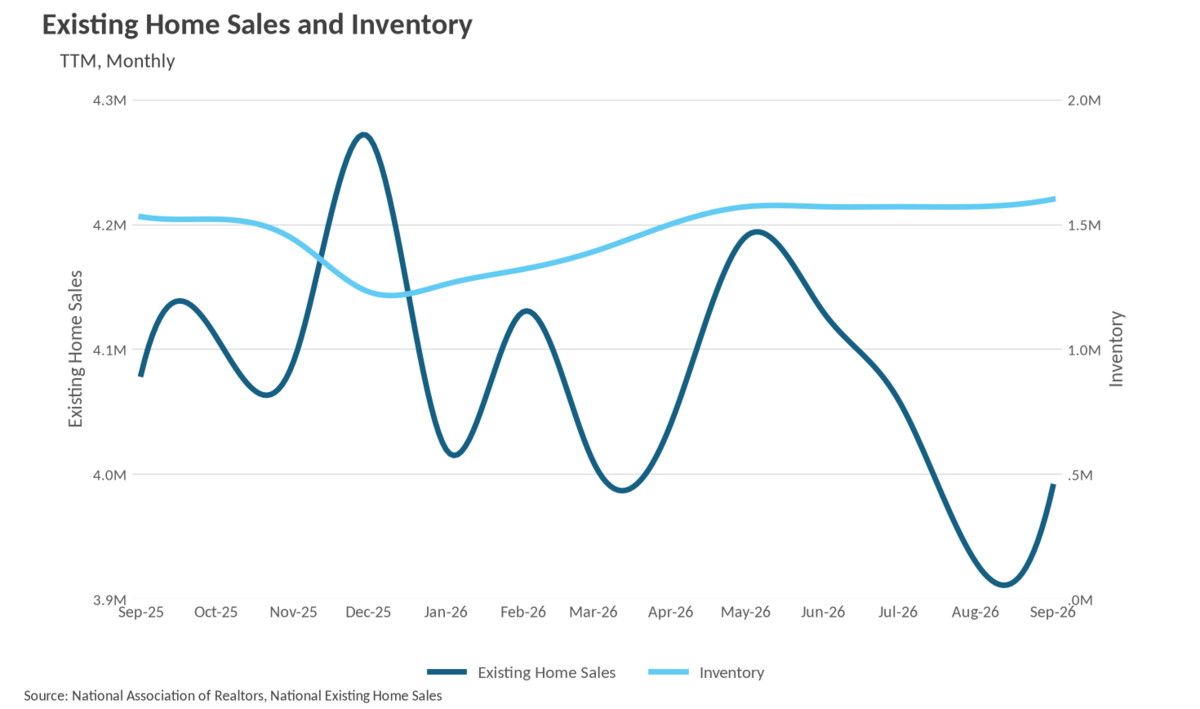
- Inventory broke out of its four-month plateau in September, climbing to 1,600,000 homes, the highest level in over a year.
- Existing home sales ticked up modestly from August but remained below last year's pace, while mortgage rates have surged into the low 7% range.
Note: You can find the charts & graphs for the Big Story at the end of the following section.
*National Association of REALTORS® data is released two months behind, so we estimate the most recent month’s data when possible and appropriate.
The spring rally has given way to a fall cooldown
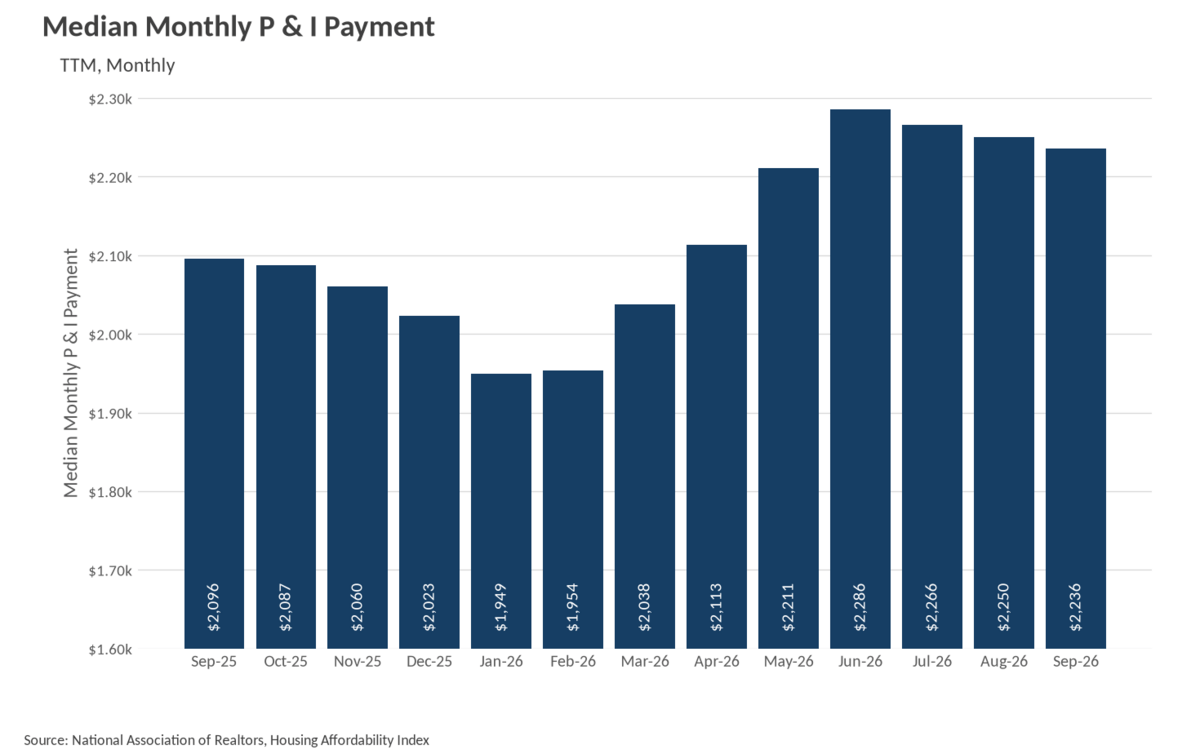
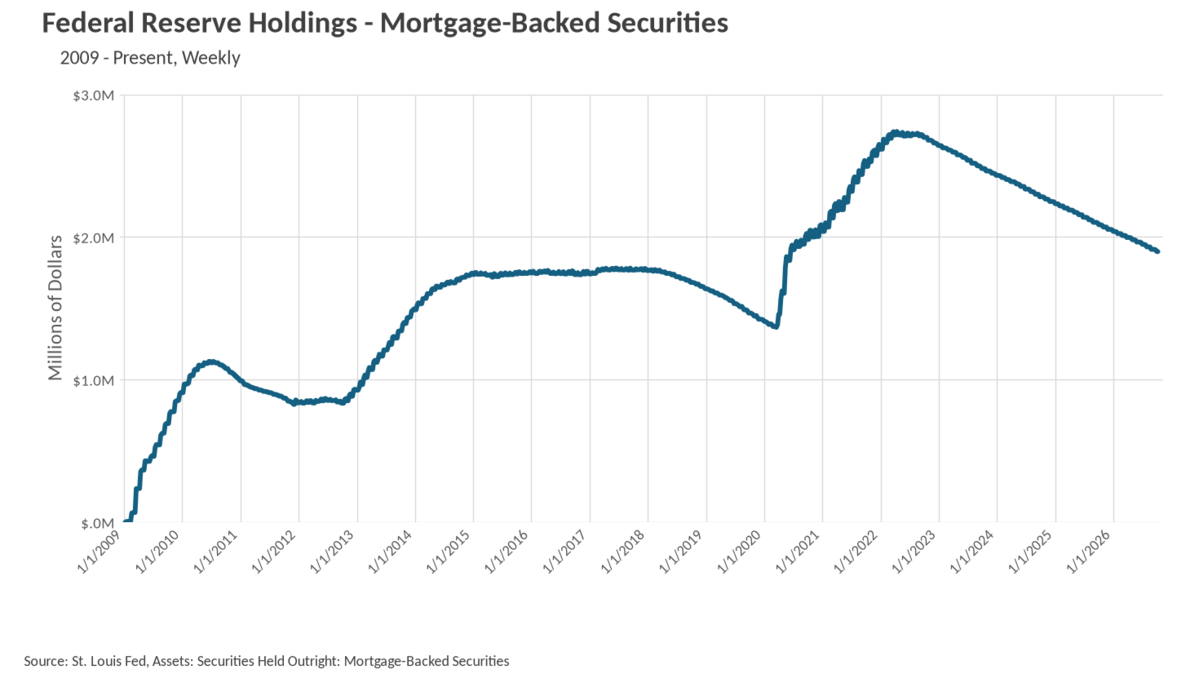
After a five-month run that carried the median sale price from $395,000 in January to a peak of $442,800 in June, prices have now retreated for three consecutive months. In September, the median home sold for $417,500, a 2.39% decline from August's $427,700 and a 5.71% drop from the June high. The one silver lining is that prices are still holding above last year's level, up 1.26% from the $412,300 median we saw in September 2025. Some of this seasonal softening is normal, as the back half of the year typically brings cooler pricing, but the affordability story is doing real damage here. Mortgage rates climbed to 6.71% in September and then jumped sharply to 7.28% in October, a full 128 basis points above the 6.00% low we saw back in March. Even with prices falling, the median monthly P&I payment sits at $2,236, which is 6.68% higher than the $2,096 buyers were paying a year ago and nearly $300 above January's $1,949. In other words, lower prices have not translated into lower payments, and with rates now pushing above 7%, the affordability squeeze is likely to intensify before it eases. Worth watching on that front: the Federal Reserve has continued to let its mortgage-backed securities holdings run off, with the balance falling from roughly $2.04 trillion in January to about $1.90 trillion in October, which removes a meaningful source of demand from the mortgage market.
Inventory breaks out of its summer plateau
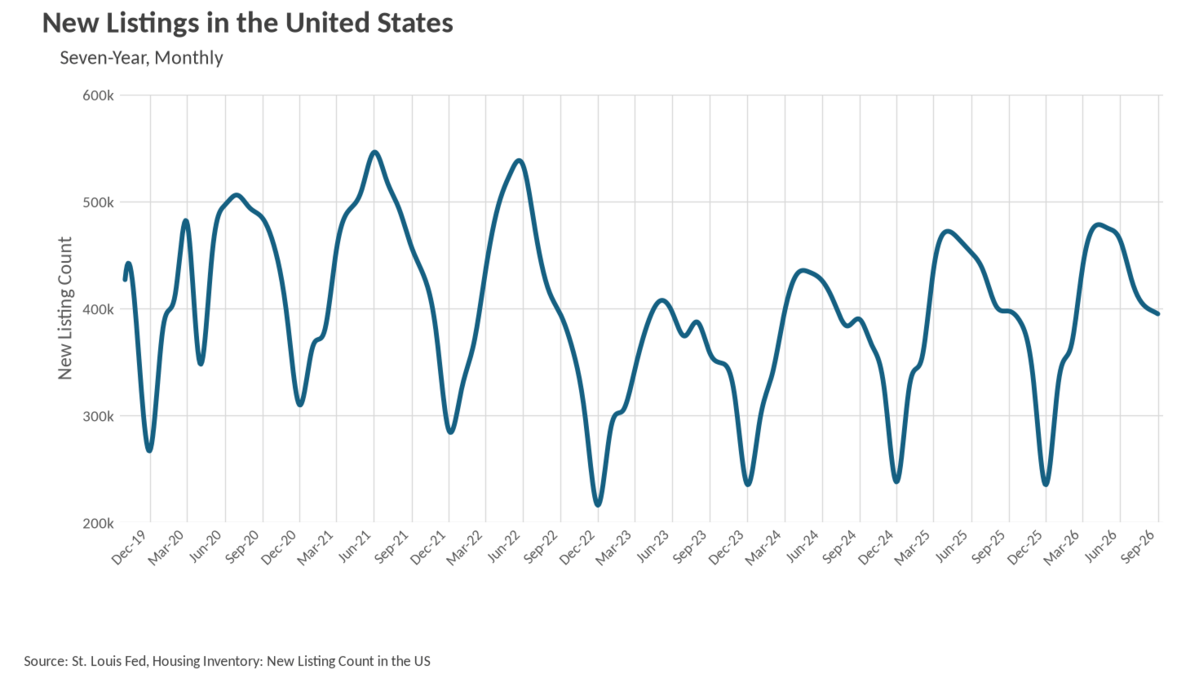
For four straight months, from May through August, inventory sat frozen at 1,570,000 homes. That changed in September, when inventory climbed to 1,600,000, a 1.91% month-over-month increase and a 4.58% gain over the 1,530,000 homes available at this time last year. This is the highest inventory level we have seen in well over a year, and notably it is rising at a point in the calendar when supply usually begins to contract. The new listings data tells a slightly different story, though. September brought 394,830 new listings to market, down 1.72% from August and down 0.65% from the 397,428 we saw in September 2025. So the inventory build is not coming from a flood of new sellers. Instead, it reflects homes sitting on the market longer and failing to clear at current prices. That is a meaningful distinction, because it suggests the supply increase is a demand problem rather than a supply surge, and it helps explain why prices have been drifting lower since June.
Sales edge higher, but remain below last year's pace
Existing home sales came in at 3,990,000 in September, a 1.53% increase from August's 3,930,000, which was the weakest reading in this entire data series. That modest uptick is welcome, but the year-over-year comparison is less encouraging: sales are down 2.21% from the 4,080,000 pace recorded in September 2025. The trend over the past several months has been clearly downward, with sales falling from 4,190,000 in May to 4,130,000 in June, 4,060,000 in July, and then 3,930,000 in August before September's small rebound. The timing lines up almost perfectly with the climb in mortgage rates, which bottomed at 6.00% in March and have risen in nearly every month since. Buyers who were energized by cheaper financing in the spring are now facing a very different math problem. With October rates at 7.28%, it is difficult to build a case for a meaningful rebound in transaction volume in the near term, though lower prices combined with the widest selection of homes in more than a year could tempt patient buyers who have been waiting on the sidelines.
The leverage has shifted toward buyers
When determining whether a market is a buyers’ market or a sellers’ market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller’s market, whereas markets with more than three months of MSI are considered buyers’ markets.
Nationally, the math now points squarely toward a buyers' market. With 1,600,000 homes available in September against an annualized sales pace of 3,990,000, the national market is carrying roughly 4.8 months of supply, comfortably above the three-month balance point and up from about 4.5 months at this time last year. Inventory is growing, sales are running below last year's pace, and prices have fallen three months in a row, which is exactly the combination you would expect in a market where buyers hold the leverage. The caveat, of course, is that having leverage and being able to use it are two different things. With rates at 7.28% in October and the median P&I payment nearly 7% higher than a year ago, many buyers simply cannot act on the discounts now available to them. Sellers, for their part, should expect longer marketing times and should price realistically rather than anchoring to June's peak. As always, real estate is a highly localized asset, which is why you should check out what's going on in your local market below in the Local Lowdown!
Big Story Data
The Local Lowdown
Quick Take:
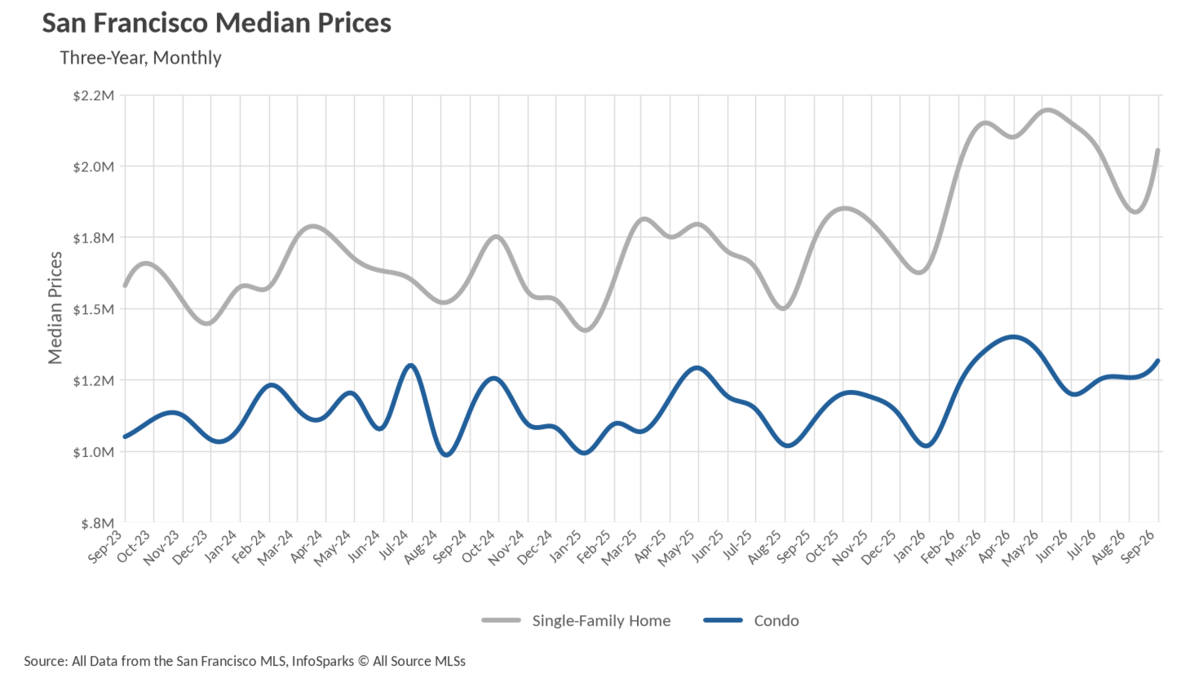
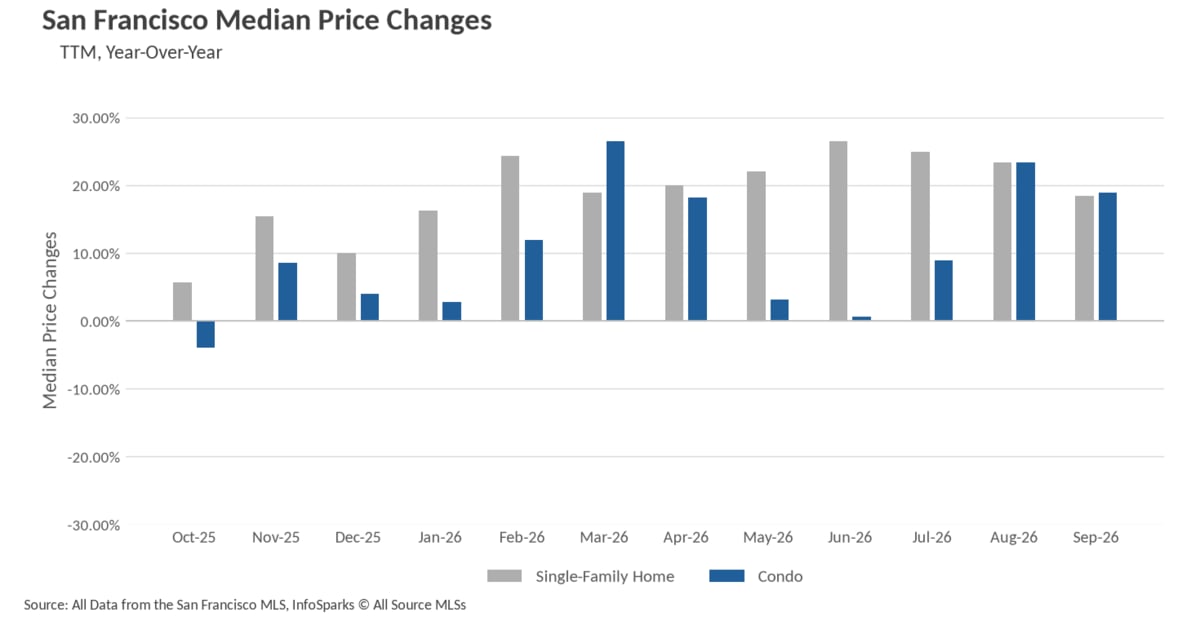
- The single-family median sale price jumped back above $2 million in September, finishing 18.4% higher than a year ago at $2,054,000.
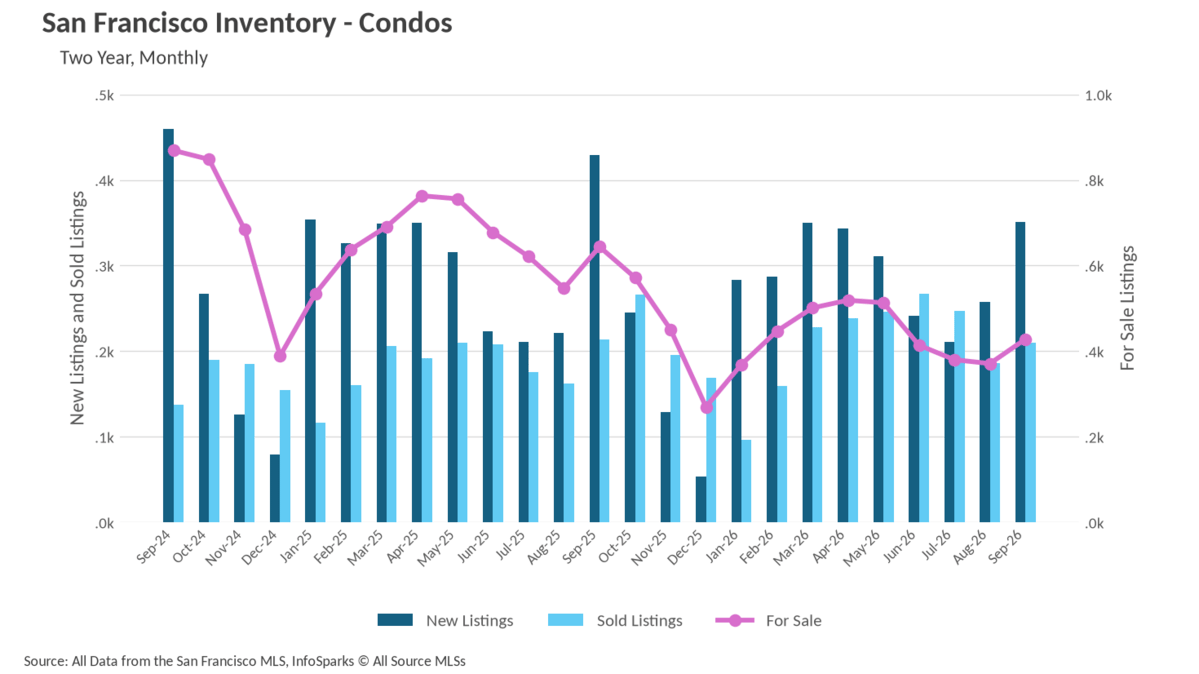
- Inventory rebounded seasonally from the summer lows but remains far below last year, with single-family listings down roughly 25% and condo listings down nearly 34% year-over-year.
- Single-family homes continue to sell in 12 days, while condos have accelerated dramatically to just 14 days, down from 26 days last September.
Note: You can find the charts/graphs for the Local Lowdown at the end of this section.
Prices rebound after a soft August, and bidding premiums hit record high
August looked like a breather for San Francisco's single-family market, with the median falling to $1,850,000, but September erased that dip in a hurry. The median sale price climbed 11.03% month-over-month to $2,054,000, putting it 18.39% above the $1,735,000 recorded in September 2025. That keeps the single-family market firmly in the $2 million-plus range it has occupied for most of 2026, a level that was simply not part of the conversation at this time last year.
The condo market turned in an equally impressive annual gain. At $1,316,500, the median condo price rose 18.87% from last September's $1,107,500 and added 4.69% from August. Condos have now posted three consecutive monthly increases after cooling off from the April peak of $1,400,000.
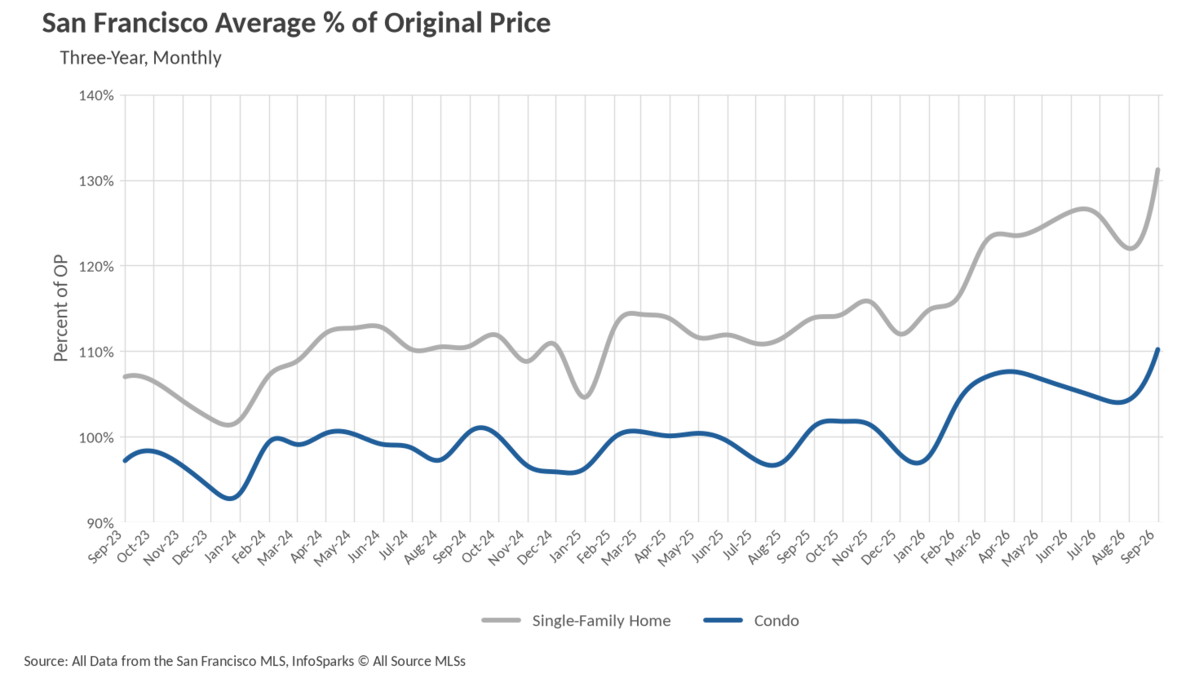
The more telling story may be what buyers are paying relative to list price. Single-family homes sold for an average of 31% above original asking price in September, the highest figure anywhere in this three-year data set and up from 14% a year ago. Condos sold for 10% over original price, also a record for this series and a sharp move from the 1% premium recorded last September. Competition is not just steady, it is intensifying.
Fall listings arrive, but the shelf is still half empty
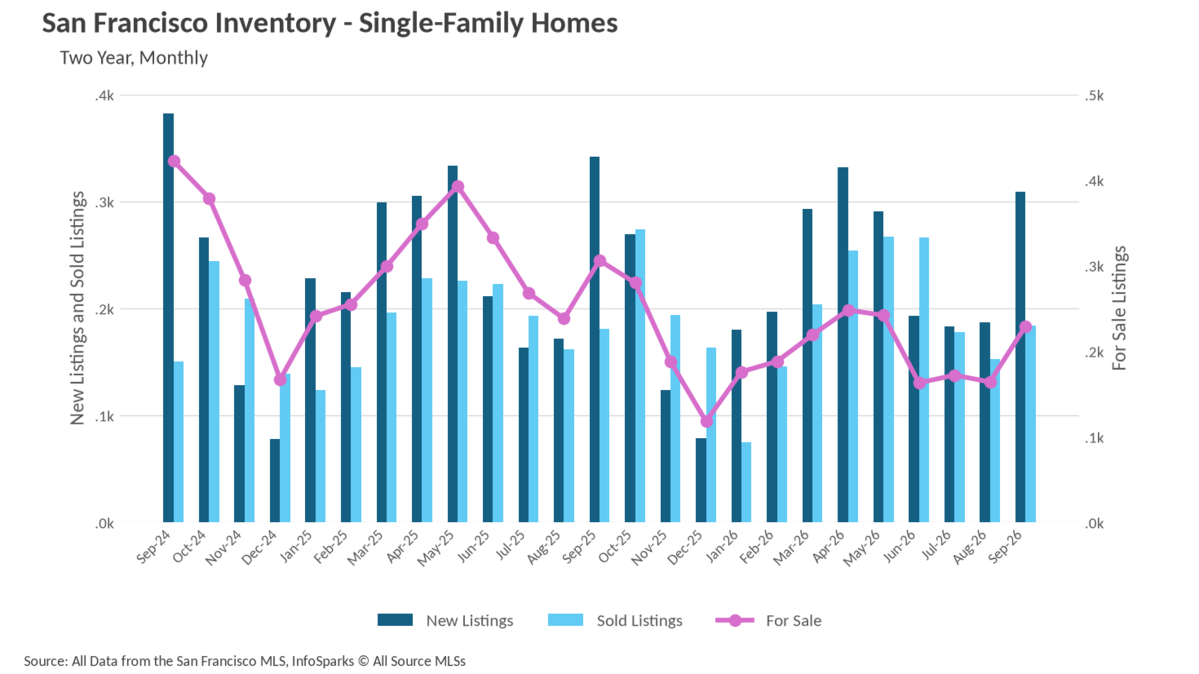
September delivered the seasonal restocking that San Francisco's market has been waiting for all summer. There were 229 single-family homes for sale at the end of the month, up 39.63% from August's 164 and the highest count since April. Sellers brought 309 new single-family listings to market, a healthy jump from 187 in August.
The problem is that this rebound still leaves the market well behind where it was a year ago. Last September there were 306 single-family homes for sale, meaning the current count represents a 25.16% year-over-year decline. New listings were also down 9.65% from the 342 brought to market in September 2025, even as sold listings held essentially flat at 184 versus 181. In other words, demand has held its ground while supply has thinned.
Condos tell a similar story with a steeper decline. There were 428 condos for sale in September, up 15.36% from August's 371 but down 33.54% from the 644 available last September. New condo listings came in at 351, an 18.18% drop from 429 a year ago, while 210 condos sold compared with 214 last September. Across both property types, roughly 650 homes were available citywide at the end of September, against about 950 at the same point in 2025.
Condos close the speed gap with single-family homes
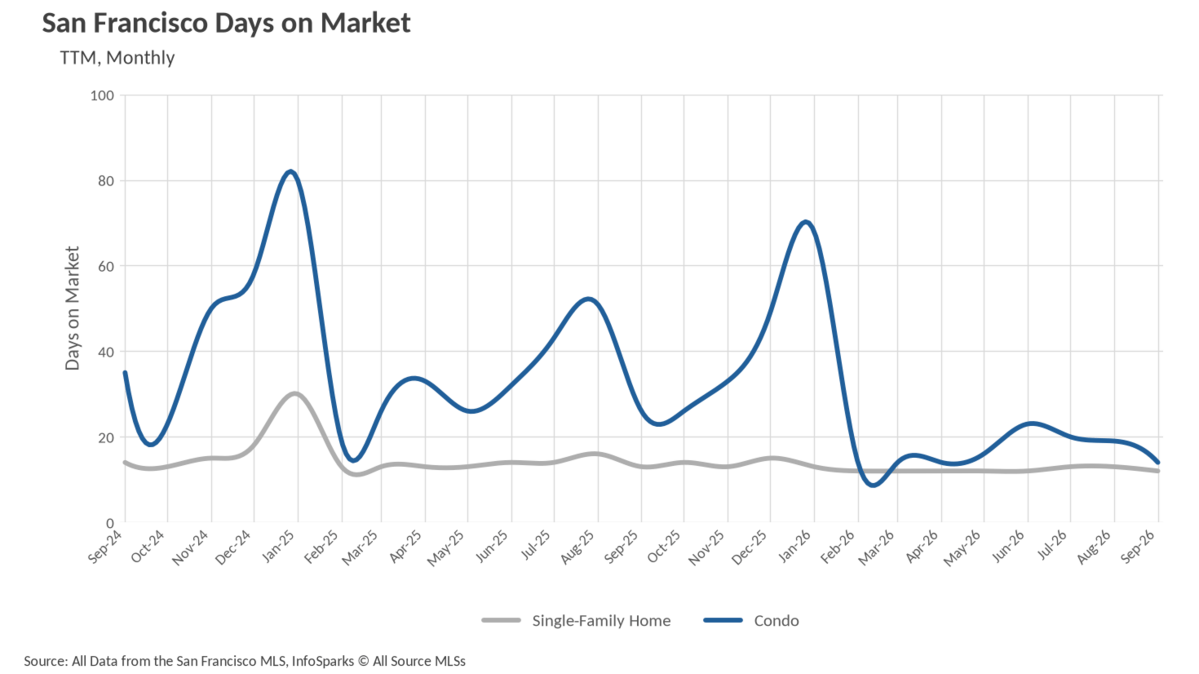
Single-family homes continue to move about as fast as they physically can. The average home sold in 12 days in September, down 7.69% from 13 days last September and consistent with the 12 to 13 day range that has held every month since February.
The condo market is where the real change has occurred. Condos sold in an average of just 14 days, a 46.15% improvement from the 26 days recorded in September 2025 and down from 19 days in August. That matches the fastest pace in this data set, equaling the 14-day readings from February through April. For context, condos spent 49 days on market in December 2025 and 68 days in January 2026. The segment that once gave buyers room to deliberate now moves nearly as quickly as the single-family market.
San Francisco remains a decisive seller's market across both property types
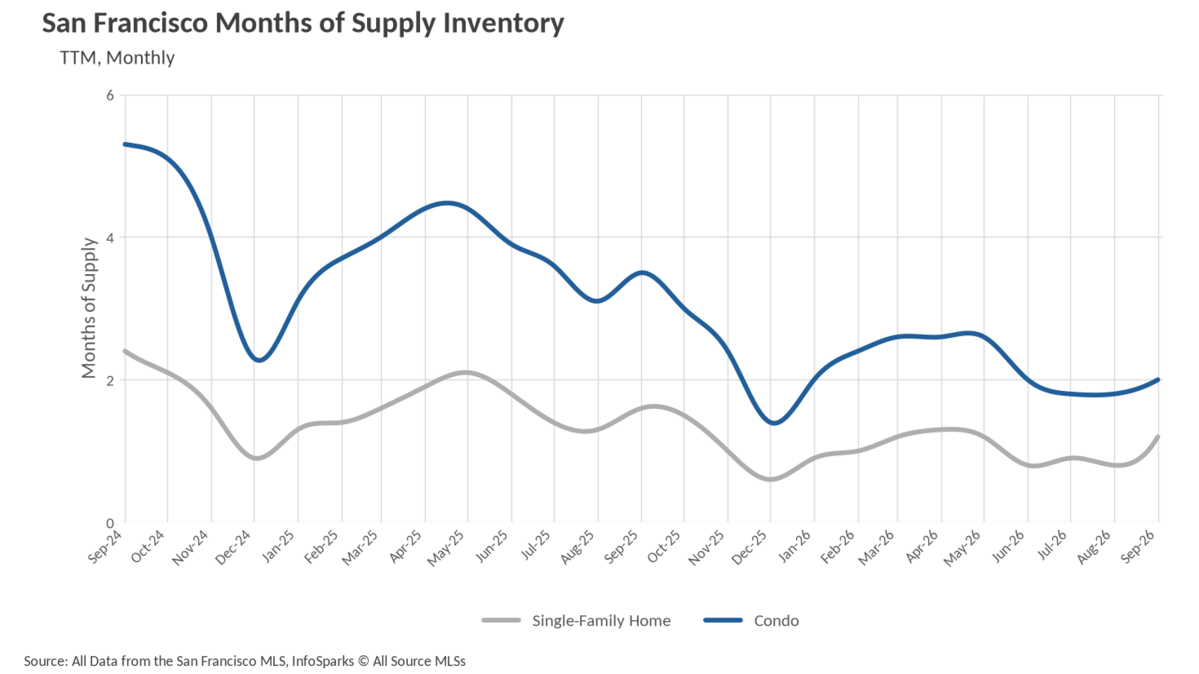
When determining whether a market is a buyers’ market or a sellers’ market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller’s market, whereas markets with more than three months of MSI are considered buyers’ markets.
San Francisco sits well below that three-month benchmark on both fronts. Single-family inventory stands at 1.2 months of supply, up from 0.8 months in August as fall listings arrived but still 25% below the 1.6 months recorded last September. The condo market carries 2.0 months of supply, essentially flat with August's 1.8 months but down 42.86% from 3.5 months a year ago. That condo figure is particularly notable, because as recently as last spring the segment was running above four months and sat squarely in buyers' market territory. It has since crossed decisively onto the sellers' side of the ledger. With record-setting sale-to-list premiums, two-week marketing times, and supply running a quarter to a third below last year in both segments, sellers retain the upper hand heading into the final months of 2026.
Local Lowdown Data